A standard personal loan agreement is a written document that records the terms of a loan between a lender and a borrower. Whether the money is being borrowed between family members, friends, business associates, or other private parties, putting the arrangement in writing can help everyone understand exactly what was agreed upon.
A well-prepared personal loan agreement typically identifies the parties, states the loan amount, explains the interest rate, establishes repayment terms, and describes what happens if a payment is missed. Using a clear personal loan agreement template can make it easier to organize these details before money changes hands.
The template below is designed as a general starting point. Loan laws and requirements can vary by jurisdiction, so parties should review the document carefully and consider obtaining qualified legal advice when appropriate.
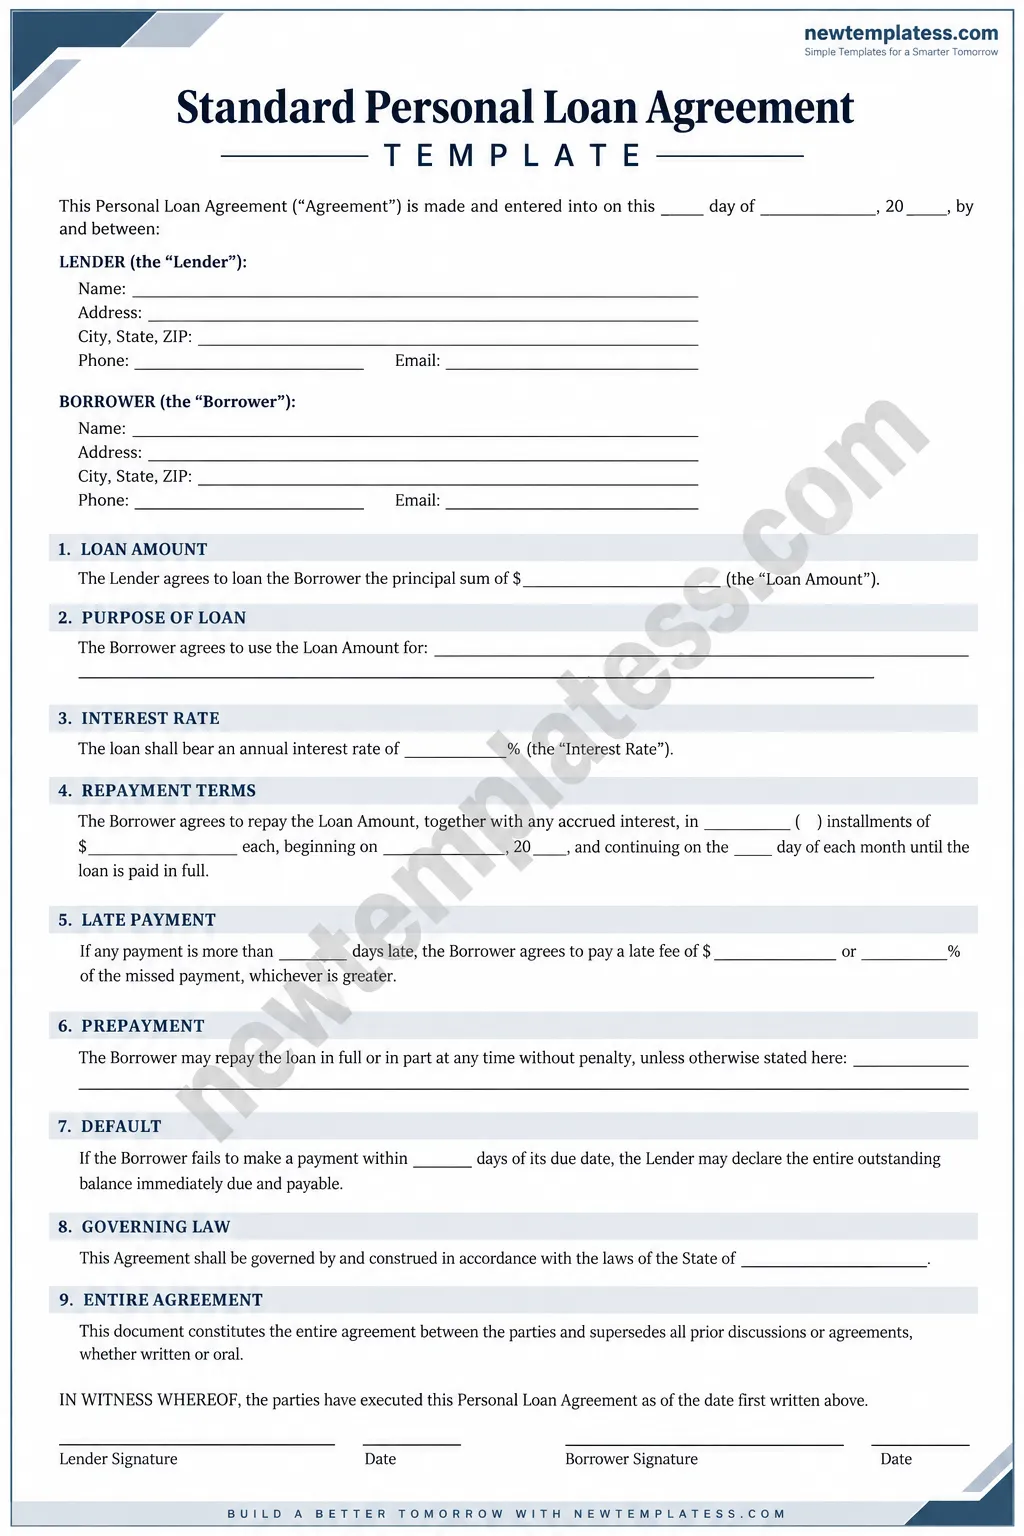
What Is a Standard Personal Loan Agreement?
A standard personal loan agreement is a written contract that explains the terms under which one party lends money to another. It creates a written record of the arrangement and helps clarify each party’s responsibilities.
Depending on the circumstances, a loan agreement may include information such as:
- The full names and contact details of the lender and borrower
- The principal amount being borrowed
- The purpose of the loan, when applicable
- The interest rate and how interest is calculated
- The repayment schedule and payment amounts
- Late payment provisions
- Prepayment terms
- Events of default and available remedies
- The governing law
- Signatures and dates
The goal is not simply to create paperwork. The agreement should make the financial arrangement understandable enough that both parties know what they are expected to do.
Why Use a Personal Loan Agreement?
Verbal arrangements can be difficult to remember or interpret later. A written agreement gives the parties a common reference point and can reduce confusion about important financial details.
A personal loan contract can be particularly useful when lending money to someone you know. Even when both parties trust each other, circumstances can change. A written document establishes expectations about when payments are due, how much is owed, and what happens if the agreed schedule is not followed.
A written loan agreement may also help distinguish a loan from a gift. Clearly documenting the expectation that the money will be repaid can provide useful evidence of the parties’ original arrangement, although applicable tax and legal rules should be considered separately.
Key Elements of a Standard Personal Loan Agreement
1. Identify the Parties
Start by clearly identifying the lender and borrower. Include their legal names and appropriate contact information. If either party is acting through a business or another legal entity, the agreement should accurately identify that entity and its authorized representative.
2. State the Loan Amount
The agreement should specify the exact principal amount being provided. It is useful to state the amount in both numbers and words where appropriate to reduce the possibility of misunderstanding.
3. Explain the Interest Rate
If the loan carries interest, identify the applicable rate and explain how it is calculated. The agreement should also account for any applicable legal limits or disclosure requirements in the relevant jurisdiction.
4. Establish Repayment Terms
The repayment section should be specific. It can state the amount and frequency of installments, the first payment date, the final maturity date, and the method or location for making payments.
For example, the agreement might provide for monthly installments until the outstanding balance has been paid in full. The parties should make sure the stated schedule is consistent with the loan amount, interest rate, and term.
5. Address Late Payments
If late fees or other consequences apply, describe them clearly. Avoid vague language that could leave the parties uncertain about when a payment becomes late or how a fee is calculated.
6. Include Prepayment Terms
Some borrowers may want to repay a loan early. The agreement can explain whether partial or full prepayment is permitted and whether any charge applies. Any prepayment provision should comply with applicable law.
7. Define Default
A default provision explains circumstances that may constitute a breach of the agreement. For example, the contract may address failure to make a required payment by its due date.
The agreement should also explain what remedies may be available after a default, subject to applicable law. Clear language can help both parties understand the consequences before a problem occurs.
8. Specify Governing Law
A governing-law clause identifies the jurisdiction whose laws will generally be used to interpret the agreement. Because contract rules differ between jurisdictions, this provision should be selected carefully.
9. Add Signatures and Dates
Finally, provide signature and date fields for the parties. Depending on the jurisdiction and circumstances, witnesses, notarization, or additional formalities may be appropriate.
How to Fill Out a Personal Loan Agreement Template
Using a template is easiest when the parties complete it systematically. Before signing, review every blank field and confirm that the information is accurate.
- Enter the parties’ legal names: Use names that accurately identify the lender and borrower.
- Enter the principal: Confirm that the written loan amount matches the amount actually being provided.
- Set the interest terms: State whether the loan is interest-free or interest-bearing and specify the applicable rate.
- Create a realistic payment schedule: Choose payment dates and amounts that both parties understand.
- Review late-payment provisions: Make sure fees and other consequences are clearly stated and legally permissible.
- Check the default clause: Confirm that the events of default and remedies accurately reflect the arrangement.
- Review governing law: Make sure the selected jurisdiction is appropriate for the transaction.
- Sign and date the agreement: Each party should retain a completed copy.
Personal Loan Agreement vs. Promissory Note
A personal loan agreement and a promissory note can both document an obligation to repay money, but they are not necessarily identical documents.
A promissory note generally focuses on the borrower’s promise to repay a specified amount according to stated terms. A broader loan agreement can contain more detailed provisions covering the relationship between the parties, including representations, default provisions, notices, governing law, and other contractual terms.
Which document is appropriate depends on the transaction and applicable law. In some situations, parties may use both a loan agreement and a promissory note.
Tips for Creating a Clear Loan Agreement
A good agreement should be precise without being unnecessarily complicated. Before signing, consider these practical tips:
- Use specific dates: Avoid unclear phrases such as “pay next month.”
- Write down the complete payment schedule: State installment amounts and due dates whenever possible.
- Keep financial figures consistent: Check that the principal, interest, installment amount, and term work together mathematically.
- Clarify payment methods: Explain how payments should be delivered or transferred.
- Keep copies: Both parties should retain the signed agreement and relevant payment records.
- Document changes: If the parties later modify the repayment schedule or another material term, put the modification in writing.
- Check local requirements: Review applicable contract, interest-rate, lending, tax, and consumer-protection rules.
Common Mistakes to Avoid
Even a simple private loan can create problems when important terms are left unclear. Common mistakes include failing to state the exact loan amount, omitting the repayment date, using an unclear interest calculation, and relying entirely on verbal promises.
Another mistake is copying a generic form without checking whether its provisions fit the transaction. A template should be treated as a starting point rather than a substitute for reviewing the actual circumstances and applicable law.
When Should You Seek Legal Advice?
A simple loan between individuals may not require extensive documentation, but professional legal advice can be useful when the transaction is substantial, secured by property, involves a business, crosses jurisdictions, includes unusual repayment terms, or raises questions about interest or regulatory requirements.
Legal requirements can vary considerably depending on where the parties are located and the nature of the transaction. A qualified professional can help determine whether additional provisions, disclosures, witnesses, notarization, security documents, or other formalities are required.
Conclusion
A standard personal loan agreement provides a practical way to document the essential terms of a private lending arrangement. By clearly identifying the parties, loan amount, interest, repayment schedule, late-payment rules, default provisions, and other important terms, the document can help establish clear expectations from the beginning.
A template can save time and provide a useful structure, but it should be reviewed and customized for the particular transaction. Before signing, both parties should make sure they understand the agreement and verify that its terms comply with applicable laws and requirements.
